Ready for the next stage of growth
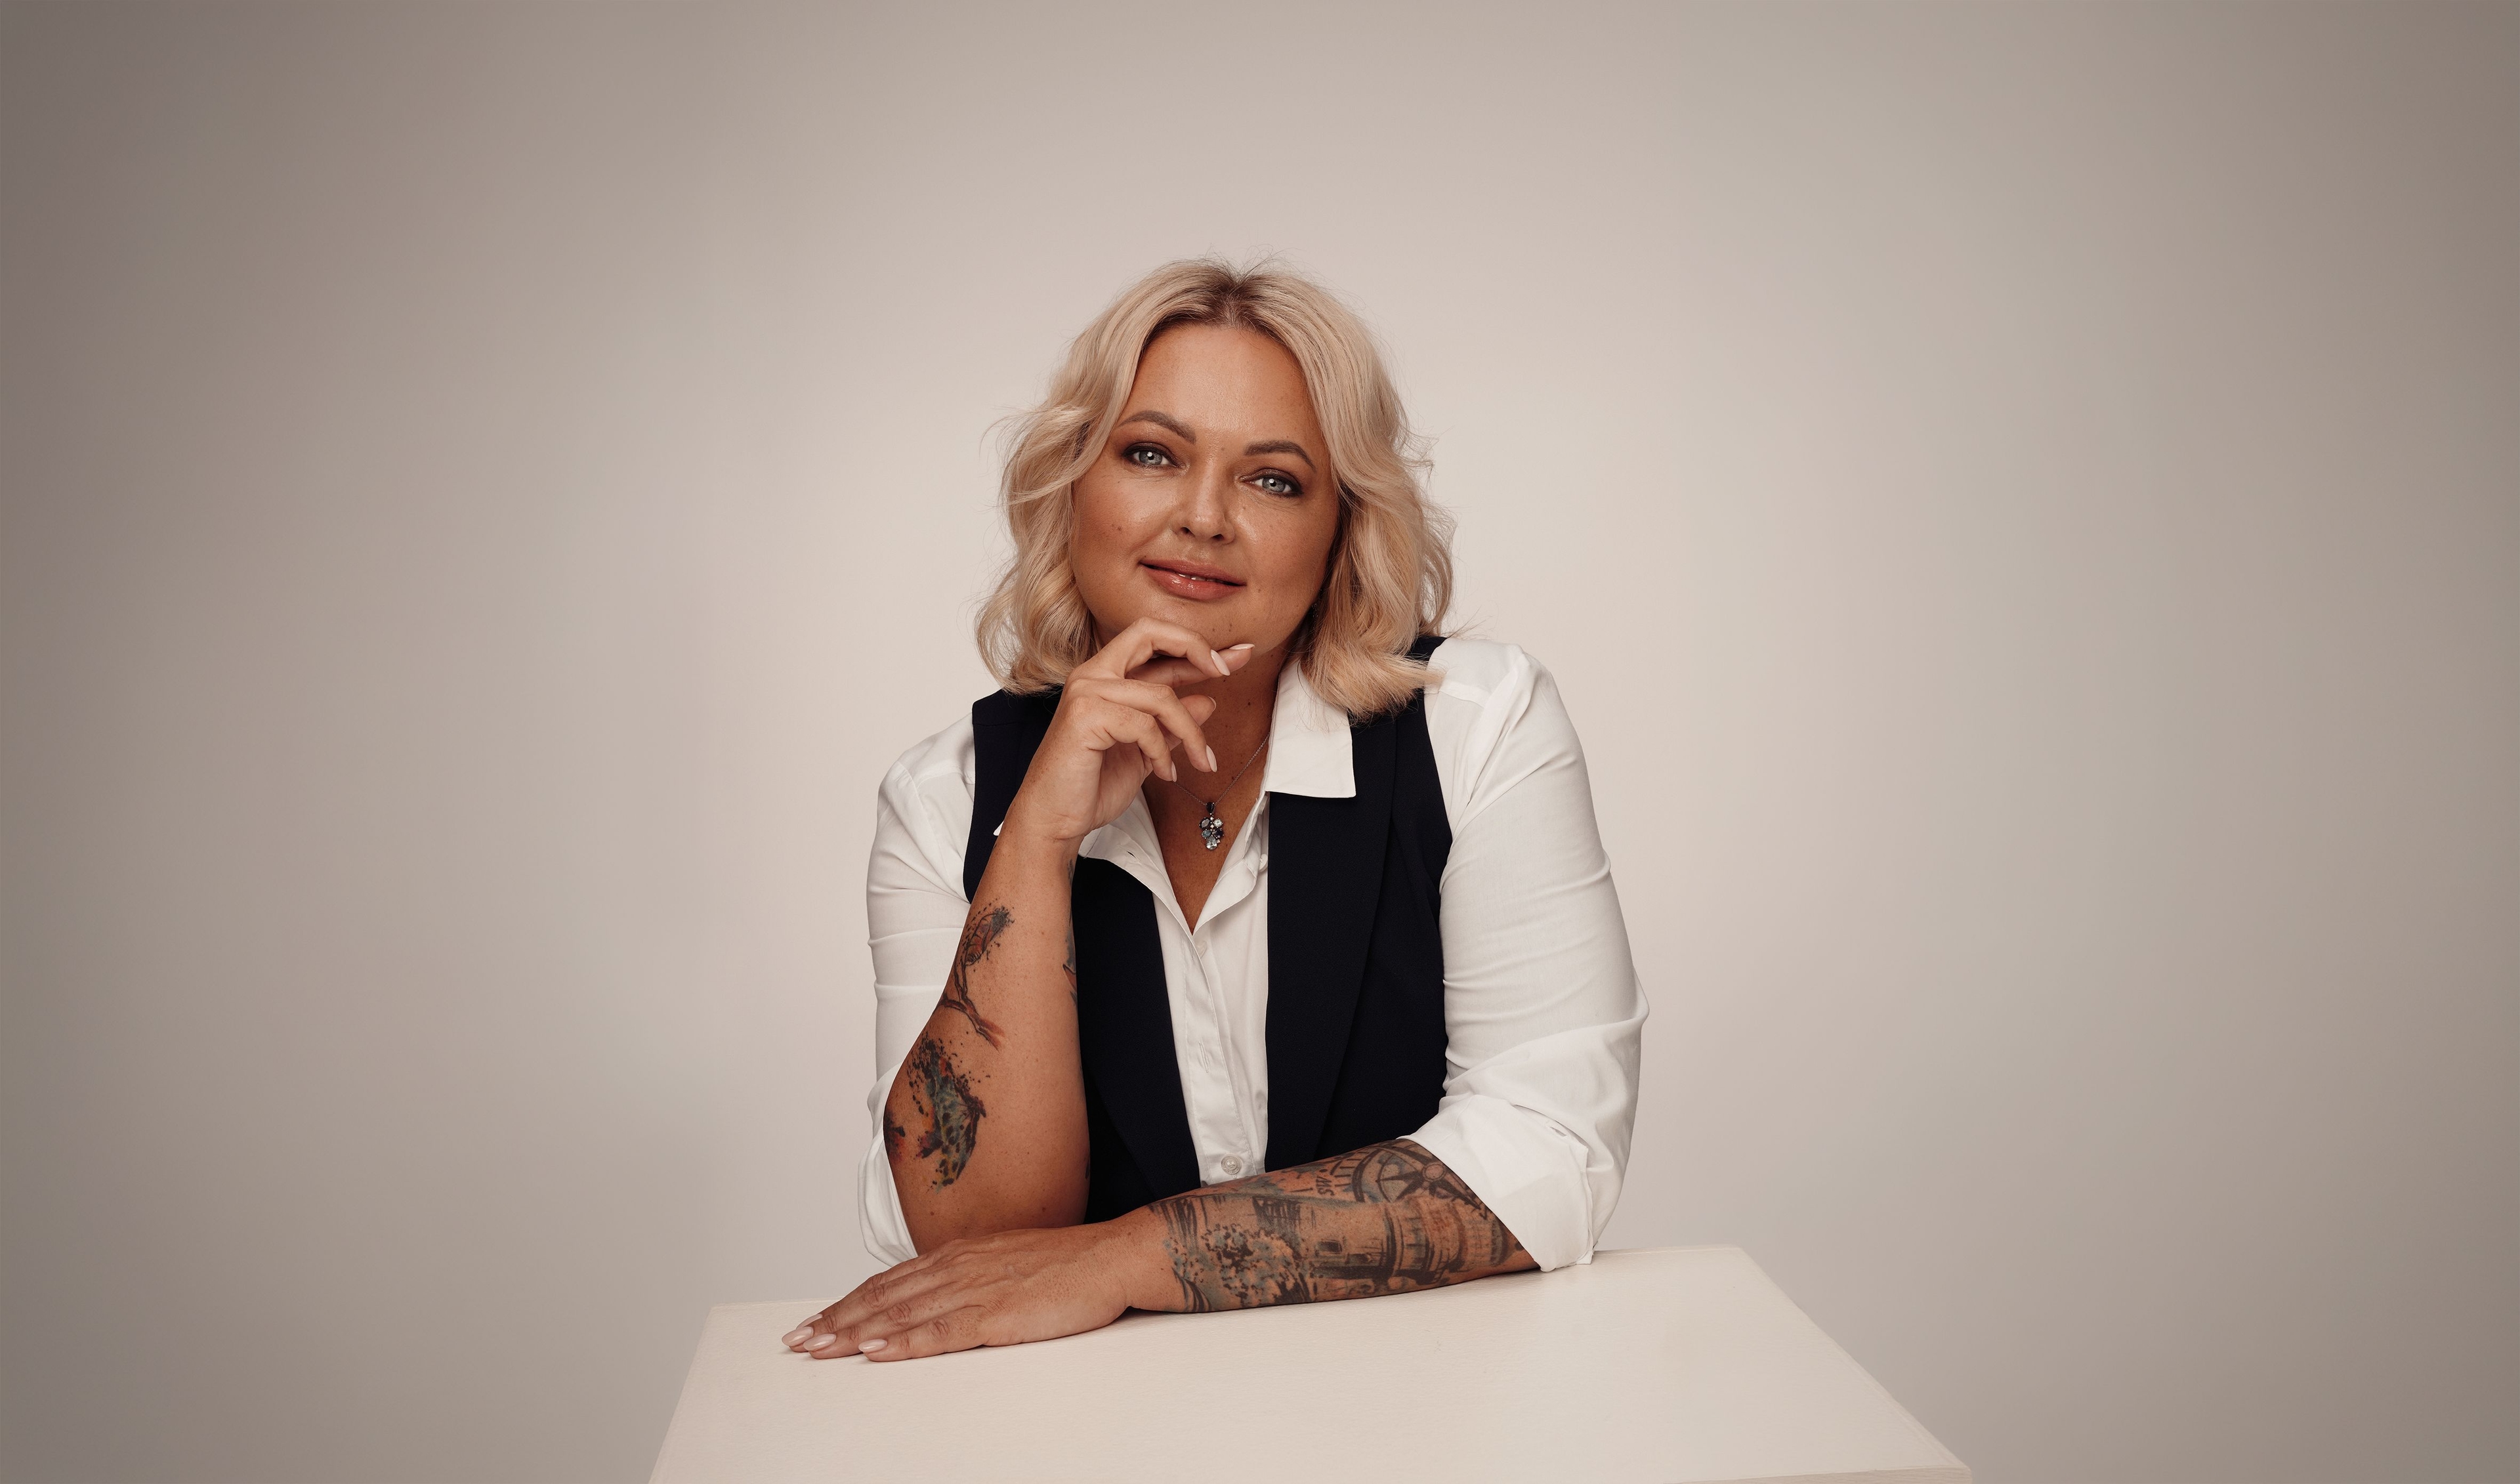
This year, Wandoo Finance launched lending operations in Lithuania, expanded its activities in Poland beyond consumer lending, and is currently considering entry into two new markets. In an interview with Dienas Bizness, Iveta Bruvele, CEO & Founder of Wandoo Finance, discusses the company’s results this year, its objectives for the next stage of development, investor sentiment, and plans for the capital markets.
Last year, in an interview with us, you promised growth and new markets. How successful have you been in delivering on those commitments?
We have delivered on our main promises. In the second quarter, we launched operations in Lithuania, where we have been offering installment loans since, making it the fifth market in which Wandoo Finance and its related entities operate. Business volumes have also continued to grow, particularly in Romania, where loan issuance increased by 23% during the same quarter. In Poland, meanwhile, the launch of lending to the self-employed and small businesses has opened a new avenue for growth beyond traditional consumer lending.
At the same time, we are in the final stage of due diligence on two acquisitions in Europe and South America. Both would add new markets to our portfolio and make an immediate contribution to revenue, as the transactions involve fully operational businesses with established systems and active customer portfolios. We expect to know the outcome soon and will then decide which direction to take. If the acquisition targets do not meet our requirements, we are also prepared to pursue the necessary licenses and enter the markets independently.
Financial performance remains encouraging, although headwinds have emerged. Strong demand for our products continues to drive business volumes, but the wider global economic environment has created additional pressure on the industry, most notably through currency movements. Both the Polish zloty and the Romanian leu have depreciated against the euro and, because lending in both countries is denominated in local currencies, this has had a short-term accounting impact on Wandoo Finance’s net profit and EBITDA. Hedging solutions are now in place to protect the business against further depreciation of the local currencies.
Compared with the first six months of 2025, net profit declined by approximately one-third, but profitability remains healthy. Wandoo Finance generated EUR 1.5 million in net profit during the first half of the year, while EBITDA remained stable at EUR 6.4 million and continued to improve from quarter to quarter. Revenue increased to EUR 40 million from EUR 28.4 million in the corresponding period last year. The second half of the year is traditionally stronger for our business, so we expect growth to accelerate significantly by year-end.
You have started lending to the self-employed and small businesses in Poland. Does this point to a broader expansion by Wandoo Finance beyond consumer lending in other markets as well?
To some extent, it does. The launch reflects our ambition to expand beyond the lending products that have traditionally formed the core of our business, but it also shows the level of maturity we have reached in Poland. After ten years in the market, Wandoo Finance is now one of the country’s largest financial service providers, and continuing to grow while remaining relevant to customers requires a broader product range.
Financing the self-employed and small businesses is a logical next step because it allows us to build on the infrastructure, customer base, sales channels, and risk management expertise we have already established. The commercial potential is also considerable, given the number of small businesses that need financing for growth or day-to-day operations but either do not qualify for a bank loan or find that the available bank products are not suitable or cost-effective.
Demand has been strong during the first few months and, if the product proves itself over the medium term, we will consider introducing similar financing in other markets. In the longer term, our ambition is to become a more versatile financial service provider capable of serving different customer groups and financing needs. I would not rule out adding card-based products and other near-prime products in the future. There is no shortage of ideas, and work on several of them is already underway.
You mentioned new markets. What criteria tell you that a particular market is right for Wandoo Finance, and what do you see there before others do?
We start with the fundamentals: market size and demand, consumer purchasing power, digital literacy, the quality of available data, and customer behavior. Regulation is equally important, particularly its predictability, because we need to understand not only the rules in force today but also the direction the market and its regulatory framework are likely to take.
We then examine the competitive landscape and whether there is still room for a product that offers customers a more convenient process, greater flexibility, or better service. Another important consideration is whether the experience and technology developed in our existing markets can be applied effectively in the new one.
The business model's economics must also work, including customer acquisition costs, potential returns, credit risk, access to funding, and currency exposure. If the market entry involves an acquisition, the due diligence covers not only the license and existing loan portfolio but also the quality and reputation of the local team and its ability to develop the business together with us.
I wouldn't say we always spot something nobody else can see. Our strength lies in bringing together a range of individual signals and recognizing early enough where our experience could provide a genuine competitive advantage. Sometimes the most attractive opportunities are found not in markets with weak competition and little regulation, but in those where demand is well established, and the rules of the game are strict and clear. Ultimately, an attractive market and good weather are not enough; we must have a convincing case for why our business can succeed there.
Where do you currently see the greatest opportunities: entering new markets, launching new products, or capturing more of the remaining potential in the countries where you already operate?
There is no single answer because each direction contributes to growth in a different way. New markets increase the company’s scale, while new products open the next stage of development in more mature markets. At the same time, existing products often still have considerable untapped potential in the countries where we already operate.
The right priority depends on the stage each market has reached. In Romania, where Wandoo Finance has operated for only three years and remains a relatively new player, there is still substantial room to grow with the existing credit line product, so the main focus is on increasing loan issuance. Poland and Spain are at a different stage: after ten years in both markets, the next phase of growth is more likely to come from new products.
Entering a new country generally produces the strongest acceleration in loan portfolio growth, although it rarely has an immediate positive impact on profit. The overall strategy therefore needs to balance all three directions, allowing Wandoo Finance to maintain its growth momentum while building a more diversified business that is not dependent on a single revenue source and can continue expanding organically without compromising financial performance.
You mentioned the launch of lending in Lithuania. Why did you choose this market? From the outside, it appears to be quite a bold move, given the country’s relatively small size and the level of competition.
Lithuania is a relatively small market, but it also has a stable economy, clear regulation, and well-developed digital financial services. Strong competition is not, in itself, a reason to avoid a country. On the contrary, it pushes us to become better and compete by offering a better product and higher-quality customer service. Ultimately, customers will choose providers that meet their needs quickly and efficiently, offer lower costs than competitors, and provide a transparent process.
Geographical diversification is also an important part of the Wandoo Finance strategy. If we enter a relatively higher-risk region such as South America in one year, the next step may be a more familiar and mature European market. Lithuania’s proximity to Latvia was therefore an important factor. Our management center and head office is in Riga, and we understand Lithuanian customers, their habits, the local business environment and culture, as well as the regulatory landscape. All the main criteria are aligned.
Lithuania is not expected to become the largest market in the Wandoo Finance portfolio. The objective is to build a well-run and profitable business that makes a meaningful contribution to the company’s consolidated results.
Thinking back to our first conversation several years ago, I remember that you spoke about issuing bonds on the stock exchange. Where do those plans stand, and how are you currently financing the company’s growth?
Those plans are still very much in place. To date, Wandoo Finance has successfully financed its growth through private debt and P2P platforms. These sources provided all the funding required to support the growth planned and delivered over the past several years, so there was no reason to rush into a bond issue and incur the associated costs before the business scale justified it.
As the company grows, both the amount and structure of the required financing change. The next step will be to attract institutional debt from investors in the Baltics and Western Europe. This would allow us to raise a larger amount through a single transaction, secure the funding for a longer period, and plan future growth with greater certainty, while also reducing the overall cost of capital.
A successful institutional debt raise would demonstrate Wandoo Finance’s maturity to the capital market and help us prepare the procedures and documentation required for the next stage. I would describe it as an entrance examination before entering the bond market.
We are already holding regular discussions with potential partners about a future bond issue. This involves assessing the cost of funding, investor sentiment, market and economic conditions, and bond issues completed by comparable companies, while also considering the appropriate size and structure of our own offering.
A public bond issue will make sense once the funding requirement is large enough to justify the transaction costs and the additional reporting, governance, and other obligations that come with it. EUR 2–3 million can be raised privately, whereas the capital market becomes attractive and cost-effective when the requirement reaches EUR 8 million or more. If everything develops according to plan, a bond issue could take place within the next two years.
News of rising geopolitical tensions caused by Russia’s actions and rhetoric has become an almost daily occurrence. Foreign intelligence services are openly expressing concern about the outlook for the Baltic region, while senior US officials are traveling to Moscow in an effort to reduce the temperature. How are your investors reacting, and how are you responding?
Investors are increasingly asking how Wandoo Finance would respond in a worst-case scenario, with most concerns focused on business continuity and asset security. That is entirely understandable because investing in a company also creates exposure to the region in which it operates and to that region's realities and risks. Nobody wants to put capital they have worked hard to build at unnecessary risk.
Shortly after Russia launched its full-scale invasion of Ukraine, we began reducing the company’s operational and systemic dependence on the Riga office. As a result, lending and debt collection in Spain no longer depend on whether electricity and internet access are available in Latvia. Our country operations can also make decisions locally, as each business has managers and specialists with the expertise required to run it independently.
We are now further strengthening our business continuity procedures to ensure they cover every layer of the business. Protecting the servers is not enough; the plans must also cover employees, contractual obligations, physical assets, and other critical areas. I sincerely hope nobody in Latvia or elsewhere in the Baltics ever needs to activate these plans, but preparedness is never wasted.
At the same time, we trust Latvia’s allies and security services. The most important thing is to keep a cool head, recognize the methods used in information warfare, prepare for the worst, and remain vigilant.
To what extent are the plans to relocate the holding company to Luxembourg connected with the geopolitical situation? Could some investors see the move as confirmation that their concerns are real?
The planned relocation is connected to both issues we have just discussed: access to capital and the geopolitical situation. Capital raising is the primary consideration because, for example, it will be much easier to approach a German investor with a holding company based in Luxembourg than with a company registered on Lielirbes Street in Riga.
Geopolitical considerations also matter, including the option of moving some assets to a safer jurisdiction. I do not see that as confirmation that investors’ concerns are justified; rather, it shows that we are managing the risks rationally and taking appropriate steps to protect both our own interests and those of our investors.
Wandoo Finance now issues loans in five countries, and the company’s structure will become broader over the coming years. We therefore need a legal structure that clearly and transparently organizes the subsidiaries, while also supporting future capital raising, cash flows between subsidiaries, and the holding of certain assets.
Luxembourg is a well-established jurisdiction in international finance, with a clear and predictable legal framework, which makes it a suitable location for the holding company. The relocation would concern the company’s legal and ownership structure, not the day-to-day management of the business. The Wandoo Finance head office and management team will remain in Riga.
If the holding company is based in Luxembourg, why keep Latvia as the head office location?
There are several important reasons, starting with the availability of highly qualified specialists in the areas a modern digital finance company depends on, including information technology, data analytics, risk management, and product development. A strong fintech sector has developed in the region over the past 10–15 years, creating a pool of people who helped build the industry, have worked through different economic cycles and have accumulated valuable knowledge and experience. That level of expertise cannot be bought or recreated overnight.
The domicile of the holding company and the location of the head office are also two separate matters. Luxembourg may offer advantages in terms of legal structure and access to international funding, but the company’s core expertise, management team, and most of its central functions are already based in Riga. There would be neither an economic nor a practical reason to relocate them elsewhere.
Finally, I am Latvian, Wandoo Finance is a Latvian company, and a large part of our team works here. I want the company’s international growth to continue creating value for the Latvian economy by providing well-paid jobs, paying taxes, and building expertise that supports the wider industry's development. Riga will therefore remain the head office of Wandoo Finance.
How has your own role at Wandoo Finance changed as the company has grown? You previously stepped away from CEO responsibilities for a period but later decided to return. What prompted that decision?
My role has changed considerably over time. In the early days, I was closely involved in the company’s daily operations and every practical detail, including the smallest ones, because I was Wandoo Finance’s first and only employee. As the company grew, my role shifted toward building a strong team, learning to trust it, delegating responsibility, and focusing more on the overall direction of the business.
At one point, I stepped away from the leadership role to pursue other projects and look at the company from the outside. That period gave me the distance to understand two things. First, we had built a strong team capable of running the business successfully without my involvement in every decision. Second, I realized that I did not want to be merely an owner who watched the company develop from the sidelines, waited for dividends, and perhaps attended a supervisory board meeting once or twice a year.
I enjoy building a business, working with people, solving difficult problems, and feeling that we are creating something bigger together. I am simply not someone who can sit on the sidelines. Returning to the leadership role was therefore not a decision driven by duty or necessity, but a conscious choice to do work that genuinely excites me and where I believe I can contribute the most.
If we had a crystal ball on the table that allowed us to look into the future, what would the future of Wandoo Finance look like?
Let us assume the crystal ball shows us five years into the future. By then, I expect the Wandoo Finance portfolio to include another four to six markets, with the company having established a stronger position in the global financial sector. This cannot simply be about adding more points to the map; each new country must become a strong, profitable, and well-run business with a clear role in the company’s overall development.
The product range should also be considerably broader. Consumer lending will remain one of our core pillars, but it will be complemented by other lending and payment products. By then, Wandoo Finance may also have obtained an electronic money institution license or a specialized credit institution license, allowing us to offer customers a much more comprehensive range of financial services.
The company’s maturity should also be reflected in the way it raises funding. I hope that, within five years, Wandoo Finance will have successfully completed its second bond issue on the Nasdaq Riga and established lasting relationships with a broader range of institutional investors.
In short, Wandoo Finance will be larger, more diversified, and financially stronger, while retaining the qualities that have brought us this far: a strong team, the ability to move quickly, the confidence to make bold decisions, and the entrepreneurial spirit to keep moving forward.